What Is PayFi, and Where Does Its Yield Come From?
A guide to payment finance: how short-term payment credit works, where the yield comes from, and the risks stablecoin depositors should understand.
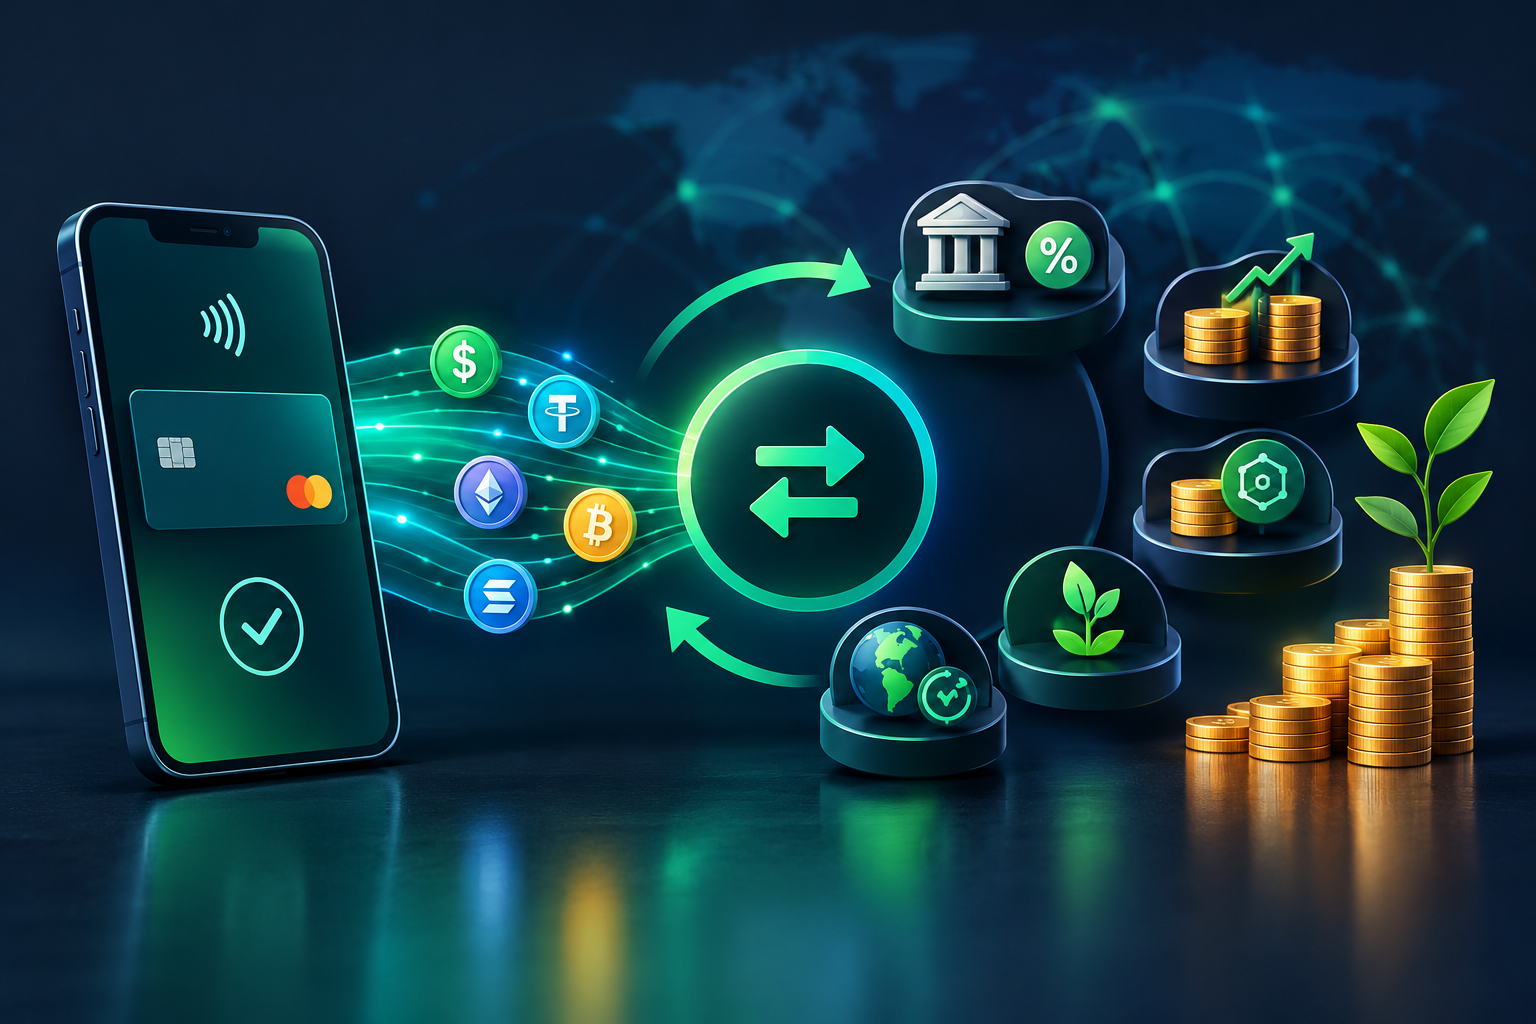
PayFi yield comes from payment companies paying a fee to borrow short-term working capital. It does not come from token emissions or leveraged trading. That one fact explains most of what makes PayFi different from the rest of on-chain yield.
If you hold stablecoins, you have probably noticed that much of the yield on offer depends on crypto markets themselves. When leverage demand falls, so does the rate. PayFi takes a different route: it lends stablecoins to businesses that move money across borders and need liquidity for a few days at a time.
This post explains what PayFi is, the problem it solves for payment companies, where the yield actually comes from, and the risks you should understand before depositing.
What PayFi is
PayFi is short for payment finance: using on-chain capital to fund real-world payment flows. Stablecoin holders supply the money. Licensed payment businesses borrow it to settle transactions, then repay it once their customers' funds arrive.
It sits within the wider real-world asset (RWA) category, alongside tokenised treasuries and private credit. What sets PayFi apart is how short and how tied to real activity each loan is. A typical credit lasts days, not months or years, and each one is linked to a specific payment that is already under way.
Stablecoins make this practical. They settle in minutes, work on weekends and bank holidays, and can move between countries without a chain of correspondent banks. That makes them a natural fit for financing payments, which are themselves about moving money quickly.
The problem: money parked before it moves
Cross-border payment companies have to hold cash in each destination country before they can pay out there. This is called pre-funding. When a business in London pays a supplier in Lagos, the payment company pays the supplier from money it already holds in Nigeria, then collects from the sender afterwards.
That parked money earns nothing and cannot be used elsewhere. Every new country a payment company enters needs another pool of it. The more a business grows, the more of its own capital ends up sitting idle in accounts around the world.
The gap between paying out and getting paid back is usually short, often between one and seven days. But it happens constantly, across every corridor the company serves. That creates a steady, repeating need for short-term liquidity.
Where the yield comes from
The yield is the fee a payment company pays to borrow stablecoins instead of tying up its own cash. It is cheaper for the company to pay that fee than to keep capital idle in every market, so it has a real commercial reason to pay.
The cycle works like this:
- Depositors put stablecoins such as USDC into a vault.
- A payment company draws a credit from the vault at the moment it needs to settle a payment.
- It pays out to the recipient using that liquidity.
- When the sender's funds arrive, usually within days, the company repays the credit plus a fee.
- The fee, after costs, flows back to depositors as yield, and the capital is ready to lend again.
Because each loan is so short, the same capital can be lent many times in a year. A small fee on each short loan adds up to a meaningful annual rate. That is why short-duration payment credit can target double-digit yields without long lock-ups.
In short, the return is paid by a business for a service it values, out of cash it is already due to receive.
How it differs from typical DeFi yield
PayFi yield depends on demand for cross-border payments, not on the mood of crypto markets. That makes it largely uncorrelated with token prices.
| Typical DeFi lending | PayFi credit | |
|---|---|---|
| Who pays the yield | Traders borrowing for leverage | Payment companies funding settlements |
| What drives demand | Crypto market activity | Real cross-border payment volume |
| Loan length | Open-ended | Usually days |
| What secures it | On-chain crypto collateral | Confirmed payment receivables, plus legal agreements |
| Link to crypto prices | High | Low |
The trade-off is that PayFi relies on real-world parties and legal agreements, not just code. That brings a different set of risks.
The risks to understand
PayFi yield is not risk-free, and a higher target yield reflects real risks. The main ones are:
- Credit risk: a borrower may fail to repay, for example if it becomes insolvent.
- Counterparty and fraud risk: the payment flows backing a loan could be misreported.
- Legal and jurisdiction risk: recovering money may depend on enforcing contracts in another country.
- Concentration risk: a vault lending to only a few borrowers is more exposed to any one of them.
- Smart contract risk: bugs in vault code could put deposits at risk.
- Liquidity risk: withdrawals may depend on loans being repaid first.
Good PayFi platforms reduce these risks rather than ignore them. Look for careful borrower checks, lending only against payments that can be verified, legal structures that give lenders enforcement rights, limits on exposure to any single borrower, audited contracts, and regular public reporting.
How Paravel approaches PayFi
Paravel originates, underwrites and administers short-duration credit to licensed cross-border payment institutions. We lend only against confirmed payment receivables we can verify.
- Originate: we source borrowers, set terms, and put legal structures and enforcement rights in place.
- Underwrite: we decide what enters a vault, with collateral requirements and concentration limits.
- Administer: we run ERC-4626 vaults, NAV attestation, redemptions and a transparency dashboard.
Our PayFi Credit Vault I lends to licensed payment institutions, secured on payment settlement receivables, with a target yield of 11% per year paid in USDC. Paravel's smart contracts have been audited by Iosiro, and the report is available on our site.
Explore the vaults or launch the app to get started.
Target yields are not guaranteed and your capital is at risk. This article is for information only and is not financial advice.