How Is PayFi Credit Secured? Receivables, SPVs and Legal Recourse in RWA Lending
PayFi yield is only as good as the structure behind it. Here is how receivables, SPVs and legal recourse protect lenders in RWA credit.
The short answer
PayFi credit is secured by the payment itself. Each loan is tied to a specific payment that is already under way, and the money coming in from that payment is what repays the loan. Around that sits a legal structure, usually a special purpose vehicle (SPV), that gives lenders a claim they can enforce in court.
This matters because real-world asset (RWA) credit is different from DeFi lending. In DeFi, a smart contract can sell a borrower's crypto collateral automatically. In RWA credit, the borrower is a real business, and protection comes from contracts, verification and careful limits as much as from code.
If you are judging any PayFi or RWA credit product, the structure behind the yield is the thing to understand. This guide explains each layer of protection, what happens if a borrower fails to repay, and the questions to ask before you deposit.
How a PayFi facility works
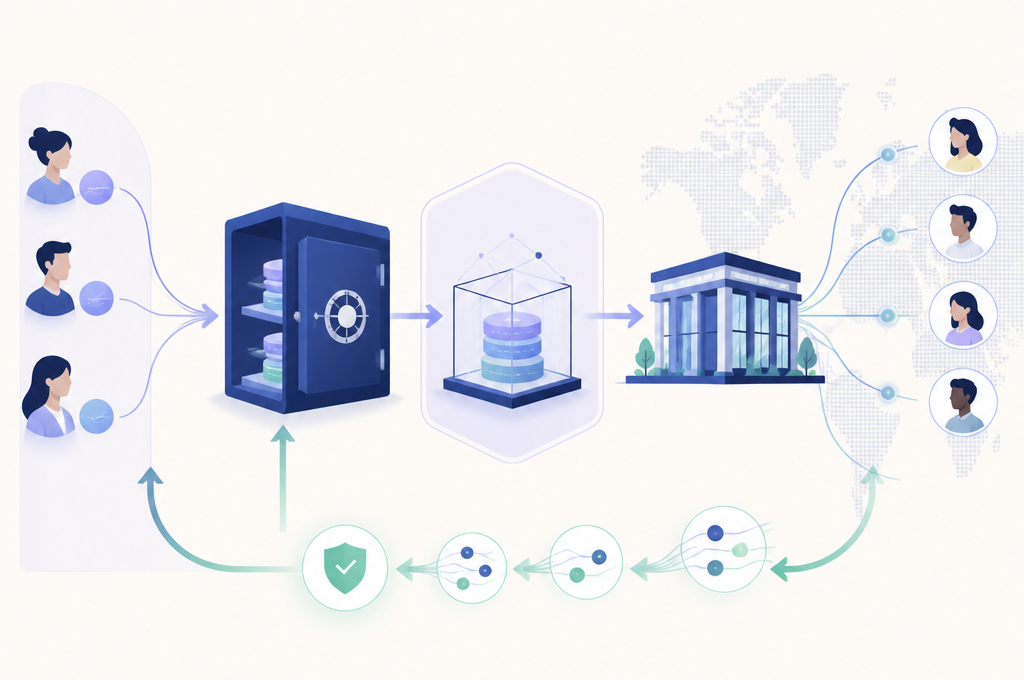
Depositors' USDC flows through the vault and SPV to a payment company, which repays from the sender's incoming funds within days.
The six layers of protection
No single layer makes a loan safe. Good PayFi structures stack several, so that if one fails, the others still protect lenders.
1. Payment receivables
A receivable is money a business is owed. In PayFi, it is the sender's funds that a payment company is due to collect after paying out to the recipient.
Lending against confirmed receivables means each loan has a clear, near-term source of repayment. The loan is not a bet on the borrower's future growth. It is an advance on cash that is already on its way, typically within days.
2. The special purpose vehicle (SPV)
An SPV is a separate legal company set up to hold a specific set of assets or loans. Lenders' money flows through it rather than directly to the borrower.
The point is separation. If the platform or the borrower runs into trouble, assets held by the SPV are kept apart from their other debts. This is often called being "bankruptcy remote". It gives lenders a cleaner claim on what backs their loans.
3. The security package
The security package is the set of legal rights lenders hold over the borrower's assets. It can include a claim over the receivables themselves, rights over the accounts where payments land, and guarantees.
These rights are what turn a promise to repay into something enforceable. They spell out what lenders can take, and when, if the borrower does not pay.
4. Verification of payment flows
The biggest risk in receivables lending is that the receivables are not real, or are pledged twice. Strong platforms check them before lending, for example by confirming payment instructions, matching them to bank or settlement data, and monitoring repayment against what was expected.
Lending only against flows that can be independently verified is what separates disciplined PayFi from unsecured lending with extra steps.
5. Borrower checks and concentration limits
Each borrower should be a licensed, regulated payment institution that passes due diligence on its finances, compliance and operating history.
Concentration limits cap how much of a vault can go to any one borrower or payment corridor. If one borrower fails, the damage to the whole vault is contained.
6. On-chain controls and reporting
The vault itself runs on smart contracts. Standards such as ERC-4626 make deposits, withdrawals and share pricing predictable and easy for others to inspect. Independent audits test that code for bugs.
Regular reporting closes the loop. Net asset value (NAV) attestations and a public dashboard let lenders see how much capital is deployed, what has been repaid and whether anything is late.
What happens if a borrower does not repay?
A missed repayment in PayFi starts a legal process, not an automatic liquidation. The usual sequence is:
- The loan is flagged as late. Short loan terms mean a problem shows up within days, not months.
- New lending to that borrower stops. Further draws are frozen while the issue is investigated.
- Lenders' rights are used. The SPV or its administrator calls on the security package, for example collecting the receivables directly or taking control of pledged accounts.
- Recovery through the courts, if needed. Where the borrower does not cooperate, the lender enforces its contracts in the relevant jurisdiction.
- Losses, if any, are shared across the vault. Any shortfall after recovery reduces the vault's NAV, which is why concentration limits matter.
Recovery can take time and may not be complete. That is a real risk, and it is part of why PayFi yields are higher than government rates.
How PayFi compares with other on-chain credit
PayFi is one part of a fast-growing market. As of 5 October 2026, RWA.xyz tracks about $8.0 billion in distributed tokenised credit and about $14.8 billion in tokenised Treasury funds. What differs most between these products is what stands behind the loan.
| DeFi lending | Tokenised Treasuries | Tokenised private credit | PayFi credit | |
|---|---|---|---|---|
| Borrower | Anonymous wallets | US government | Businesses | Licensed payment institutions |
| What secures the loan | Crypto collateral | Government debt held by a fund | Business assets, loan agreements | Confirmed payment receivables, SPV, security package |
| How a default is handled | Automatic liquidation by code | Very unlikely; issuer and custody risk instead | Legal recovery | Legal recovery, with short loans flagging issues fast |
| Typical loan length | Open-ended | Weeks to months | Months to years | Days |
| Main thing to check | Smart contracts, oracles | Issuer, access limits | Underwriting quality | Receivables verification, enforceability |
PayFi's short loan cycle is its biggest structural advantage. Capital is repaid and re-checked every few days, so a weakening borrower can be cut off quickly.
Questions to ask any PayFi or RWA credit platform
- Who are the borrowers, and are they licensed? You should know what kind of businesses borrow and who regulates them.
- What exactly secures each loan? Ask whether loans are backed by specific receivables, and how those are confirmed.
- Is there an SPV, and where is it based? The jurisdiction decides which courts enforce lenders' rights.
- What rights do lenders have on default? Look for a written security package and a named party responsible for enforcement.
- What are the concentration limits? Find out the most any single borrower or corridor can take from the vault.
- How often is NAV reported, and by whom? Regular, independent reporting is a sign of a platform with nothing to hide.
- Have the smart contracts been audited? Read who did the audit and what they found.
- How do withdrawals work? Check notice periods and whether redemptions depend on loans being repaid first.
How Paravel structures PayFi credit
Paravel takes on three roles in every facility, so one accountable party stands behind each one:
- Originate: we source licensed payment institutions, agree terms, set up the SPV, and put the security package and enforcement rights in place.
- Underwrite: we decide what enters a vault, with collateral requirements, oracle checks, concentration limits and a published rebalancing cadence.
- Administer: we run ERC-4626 vaults, NAV attestation, redemptions and a transparency dashboard.
We lend only against confirmed payment receivable flows we can verify. Facilities range from $250,000 to $25 million. Our PayFi Credit Vault I targets 11% per year, paid in USDC, and our smart contracts have been audited by Iosiro.
New to PayFi? Start with What Is PayFi, and Where Does Its Yield Come From?. When you are ready, explore the vaults or launch the app.
Target yields are not guaranteed and your capital is at risk. This article is for information only and is not financial advice or legal advice. Market figures are from third-party sources and may change.
Frequently asked questions
Is PayFi a type of RWA?
Yes. PayFi is a form of real-world asset credit. The loans fund real payments made by real businesses, and lenders' protection rests on off-chain contracts as well as on-chain code.
What is a receivable in PayFi?
It is money a payment company is owed by a sender after it has already paid the recipient. PayFi loans are advances against those incoming funds.
What does an SPV do in RWA lending?
An SPV is a separate legal company that holds the loans or assets for lenders. It keeps those assets apart from the platform's and borrower's other debts, which gives lenders a cleaner claim.
Can a smart contract liquidate a PayFi borrower?
Not in the way DeFi lending does. The borrower's collateral is off-chain, so recovery runs through the security package and, if needed, the courts.
Is PayFi safer than DeFi lending?
It carries different risks rather than no risk. PayFi has less exposure to crypto prices but more exposure to borrower credit, fraud and legal enforcement.